Written by Robert Clarke: Connecticut Licensed Real Estate Agent, License #0815837, Coldwell Banker Realty
The appraisal decides what your lender will finance on the home you want. Here is how it works in Connecticut, how it differs from an inspection, and what to do when the number comes in low.
After your offer is accepted and the inspection is scheduled, another professional shows up at the property: the appraiser. Unlike the inspector, who is there for you, the appraiser is there for your lender, and the report they produce can shape the entire transaction.
The good news is that an appraisal does not have to be stressful if you understand what it is measuring, how it works, and what your options are when the number does not match the price you agreed to pay.
Let's break it down the same way I would at a kitchen table over coffee: plainly, and without the jargon.
What Is a Home Appraisal?
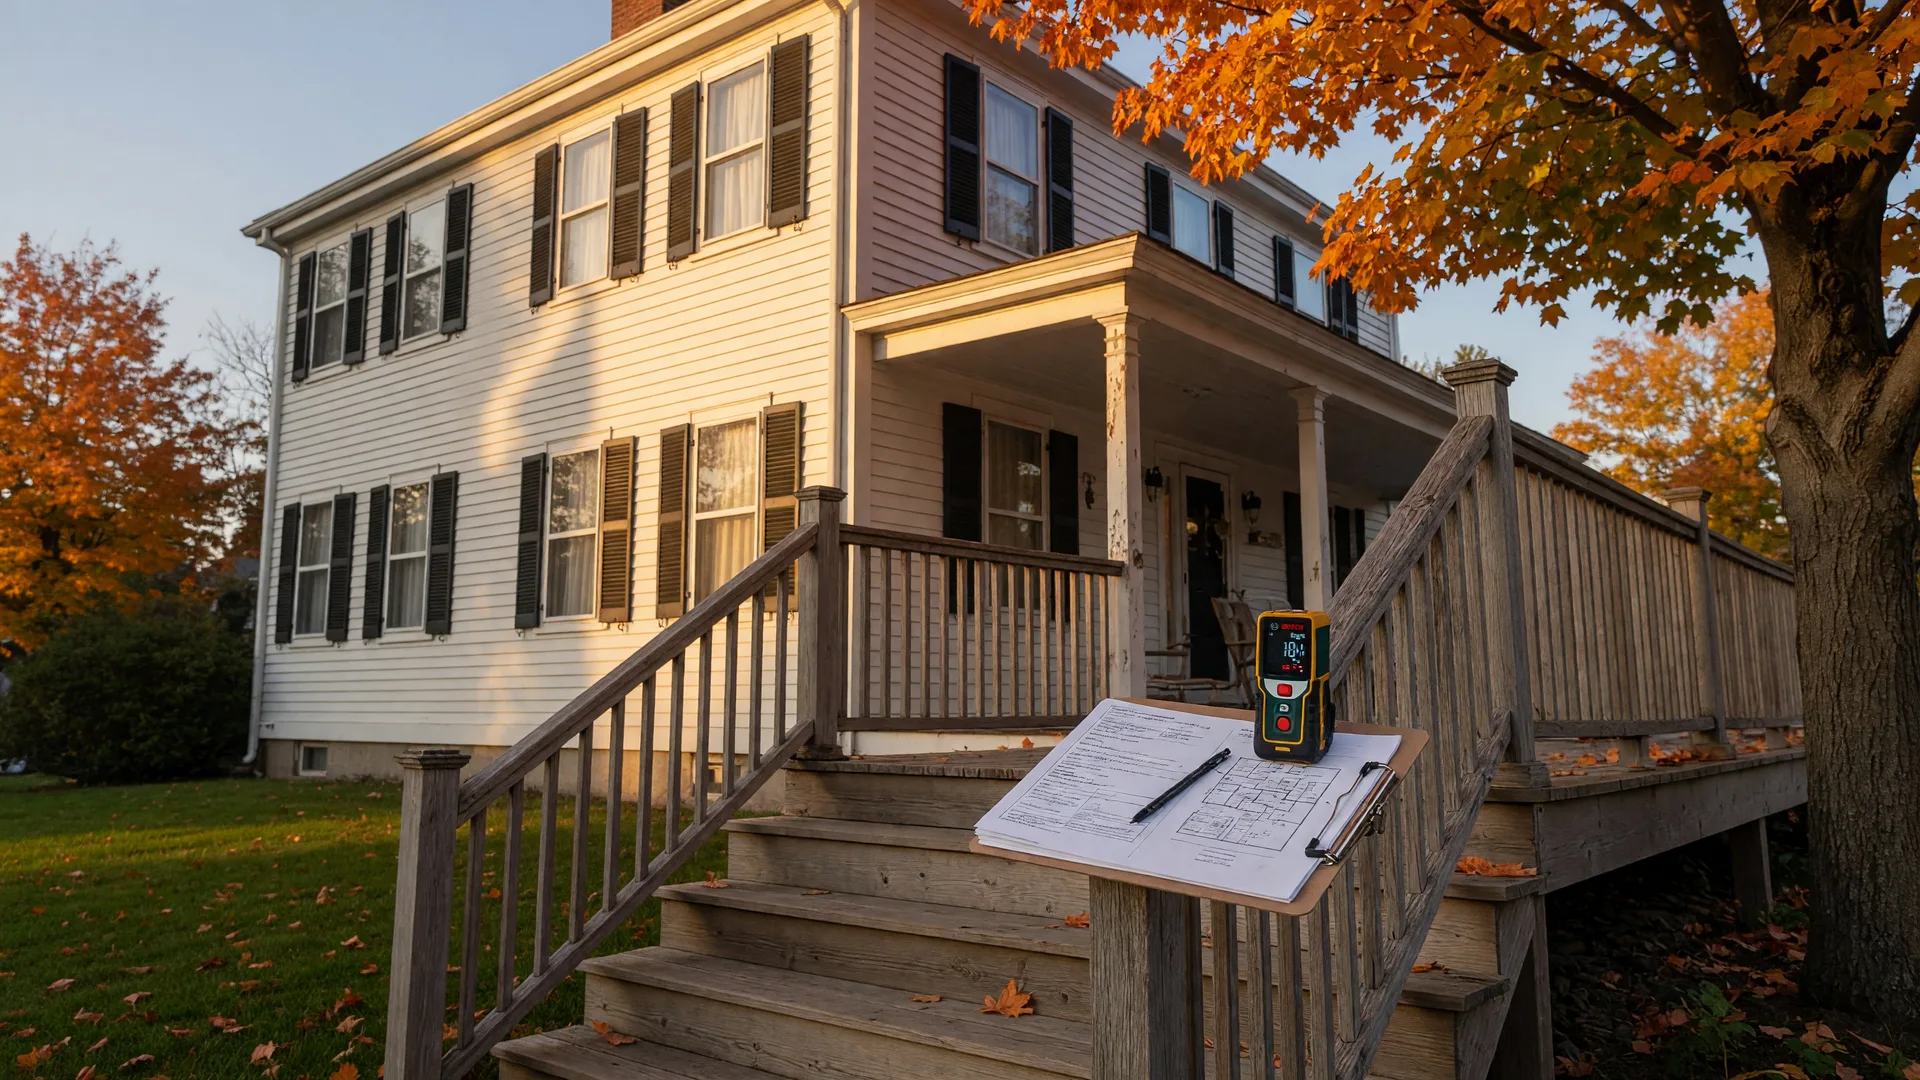
A home appraisal is an independent, professional opinion of a property's market value. A licensed appraiser visits the home, measures it, documents its condition and features, and then compares it with recent sales of similar homes nearby.
It is not the same as your agent's estimate, and it is not the same as the listing price. The appraiser has no stake in the deal. Their job is to answer one question for the lender: is this home worth what we are being asked to lend against it?
In Connecticut, appraisals are conducted by state-licensed or certified appraisers, and the report follows recognized standards so that different appraisers looking at the same home would reach broadly similar conclusions.
Why Do Lenders Require an Appraisal?
When a lender issues a mortgage, they are lending against collateral: the house itself. If the buyer stops making payments and the home goes to foreclosure, the lender sells the house to recover the loan. If the house is worth less than the loan, the lender loses money.
The appraisal protects the lender from financing more than the home is worth. By a side effect, it also protects you: it is an independent check that you are not overpaying compared with what similar homes have actually sold for.
Your lender chooses the appraiser, typically from a rotation, so the report is genuinely independent of the agents and the buyer and seller involved in the deal.
How an Appraiser Values a Home in Connecticut
The appraiser builds their opinion of value from three main ingredients:
Comparable Sales
The heart of the report. The appraiser looks for homes that actually sold recently, usually within the last three to six months, in the same neighborhood and within a reasonable distance. They adjust for differences: an extra bathroom, a basement finish, a bigger lot, or a superior condition.
Condition and Features
The appraiser walks the property, checks the square footage, counts the rooms, and notes the condition of systems like the roof, heating, and electrical. Updated kitchens and baths count, and so does deferred maintenance. Property age and overall upkeep factor in too.
Location
In New Haven, location is powerful. A few blocks can change value meaningfully: proximity to schools, parks, transit, downtown, and the neighborhood's character all flow into the appraiser's adjustments. The school district and commute profile matter to buyers, so they matter to appraisers.
From those inputs the appraiser produces a single opinion of value, expressed as a number. That number is what your lender uses for the loan-to-value calculation.
Appraisal Versus Home Inspection
People use the words interchangeably, but they are completely different reports for completely different people.
The appraisal answers "what is it worth" for the lender. The inspection answers "what is the condition" for the buyer. The inspector crawls the attic, checks the wiring, tests the plumbing, and reports on defects and repairs. The appraiser measures, photographs, and compares sales, but does not test systems or find hidden problems.
You will typically pay for both in a Connecticut purchase: the inspection directly, and the appraisal within your closing costs. Both are worth every dollar, because they are protecting you in different ways.
What Happens If the Appraisal Comes in Low?
This is the scenario buyers worry about most. Here is the reality: the lender will only finance based on the appraised value, so a gap appears between the agreed price and the loan the house can support. You have several options:
Renegotiate the Price
The seller can lower the price to the appraised value. In many cases this is the cleanest resolution, especially when the appraisal is close to the deal price. Your agent presents the appraisal to the seller's team and negotiates the adjustment.
Make Up the Difference
You can bring additional cash to closing to cover the gap between the appraised value and the agreed price. This keeps the deal at the original price, but it means a larger cash outlay, so it only makes sense when you believe the home is worth the price and you have the funds.
Split the Difference
Many deals land in the middle: the seller reduces the price partway toward the appraised value and the buyer brings the rest as additional cash. This is often the fastest path to closing when both sides want to save the deal.
Challenge the Appraisal
If the appraisal feels wrong, your agent can request a reconsideration of value. That means presenting the lender with comparable sales the appraiser may have missed, evidence of upgrades that were overlooked, and corrections to any factual errors. It does not always work, but it is a legitimate, structured process.
Walk Away
If no agreement is reached within the financing contingency, you can typically walk away and recover your earnest money deposit. The appraisal being low is a legitimate financing issue, which is exactly what the financing contingency protects against.
None of these options require you to handle it alone. Your agent manages the negotiation, and your lender manages the reconsideration process.
Low Appraisals in a Competitive New Haven Market
In a competitive market, offers can run ahead of what recently sold homes support, and appraisals sometimes lag. That is not the appraiser being difficult. In many New Haven neighborhoods, sale prices have moved faster than the comparable sales the appraiser is required to use, and those sales lag a few months behind the market.
When buyers compete for a home, experienced agents factor appraisal risk into the offer strategy: knowing when a price is supportable and when it might draw a gap, and agreeing in advance how a shortfall would be handled. That conversation belongs before you write the offer, not after the appraisal arrives.
Having a number to reach for, and a plan for the gap, is what turns an appraisal surprise into a manageable step.
Frequently Asked Questions
Who pays for the appraisal in Connecticut?
The buyer pays for the appraisal as part of their closing costs, usually a few hundred dollars for a standard single-family home. The appraisal is ordered by the lender, and the cost is typically paid at or before closing, either from the buyer's closing funds or as part of the pre-paid costs.
How long does an appraisal take?
The appraiser usually visits the property within a few days to a week after the order is placed, then completes the report over the following days. Most appraisals are done within one to two weeks in the New Haven area, though busy periods and harder-to-value properties can add time.
What if the appraisal is lower than the offer?
The lender will only lend on the appraised value, so the gap has to be covered somehow. Common options: the seller lowers the price to the appraised value, the buyer pays the difference out of pocket, the two sides split the gap, or the buyer challenges the appraisal. If no agreement is reached within the financing contingency, the buyer can typically walk away and recover their deposit.
Can I challenge a low appraisal?
Yes. Your agent can ask the lender for a reconsideration of value by providing comparable sales the appraiser may have missed, pointing out features or upgrades that were overlooked, and correcting any factual errors in the report. It does not always change the number, but it is a legitimate step with good evidence.
Does a home inspection cover appraisals?
No. An appraisal is a lender-required opinion of value based on comparable sales, condition, and location. A home inspection is a detailed condition review of the property's systems and structure for the buyer's benefit. They are separate reports, ordered from different professionals, and both are part of a typical Connecticut purchase.
Navigating Appraisals in the New Haven Market
An appraisal gap is manageable when you have the right number, a realistic plan, and a negotiator who knows the New Haven comparables inside out. I help buyers price their offers with appraisal risk in mind and help sellers position their homes to appraise on target. If you are ready to talk strategy, reach out.
Let's make sure the numbers work for your New Haven home.
Robert Clarke
Licensed Connecticut Real Estate Agent · License #0815837 · Coldwell Banker Realty
Robert Clarke brings an analytical, technology-informed approach to real estate along with a people-first style of service. His goal is to make complex real estate decisions easier to understand and help clients move forward with clear information and a practical strategy. Contact Robert at (203) 936-9004, email rob@robandvicCT.com, or visit robandvicct.com.
Disclaimer: This article is for general educational purposes and is not legal, tax, or financial advice. Appraisal requirements, timelines, and loan programs vary by lender and transaction. Your lender and licensed professionals should be consulted about your specific situation.
Related Articles
- Escrow 101: What New Haven Buyers and Sellers Need to Know
How escrow works, who holds the funds, and the typical Connecticut timeline from deposit to closing.
- How Much Does It Cost to Close on a Home in Connecticut?
A breakdown of typical buyer and seller closing costs, plus Connecticut's attorney-closing rules.
- First-Time Homebuyer's Guide: Buying a Home in Connecticut
From pre-approval and down payment programs to neighborhood choice and closing day.